 Del Bailey
Kids learn money best through small, repeated, hands-on moments, not one big lecture. The Consumer Financial Protection Bureau’s Money as You Grow program splits it by age: simple ideas like earning, waiting and needs versus wants for ages 3 to 5, habits that take shape from 6 to 12, and real financial decision-making from 13 to 21.
Updated November 12, 2026.
I have kept a household budget for years with the same discipline I bring to a workout plan. The part that made it stick was never a spreadsheet. It was saying money decisions out loud, to the people they affect, instead of handling them quietly behind a closed door. That habit is the thread running through everything below. Most of us learned about money the hard way, through a surprise fee or a bill we didn’t see coming. Kids don’t have to learn it that way. And if you’ve ever been stumped when a child asks why you can’t just get more money out of the wall, you already know most parents are teaching lessons they were never taught. It can feel like reading the instruction manual one chapter ahead of your kid, and there’s no shame in that.
None of this needs a curriculum, an app, or a lecture nobody asked for. These are ordinary habits, the same ones that reduce money stress for adults, scaled down to a kid’s world.
Start With the Physical Reality of Money
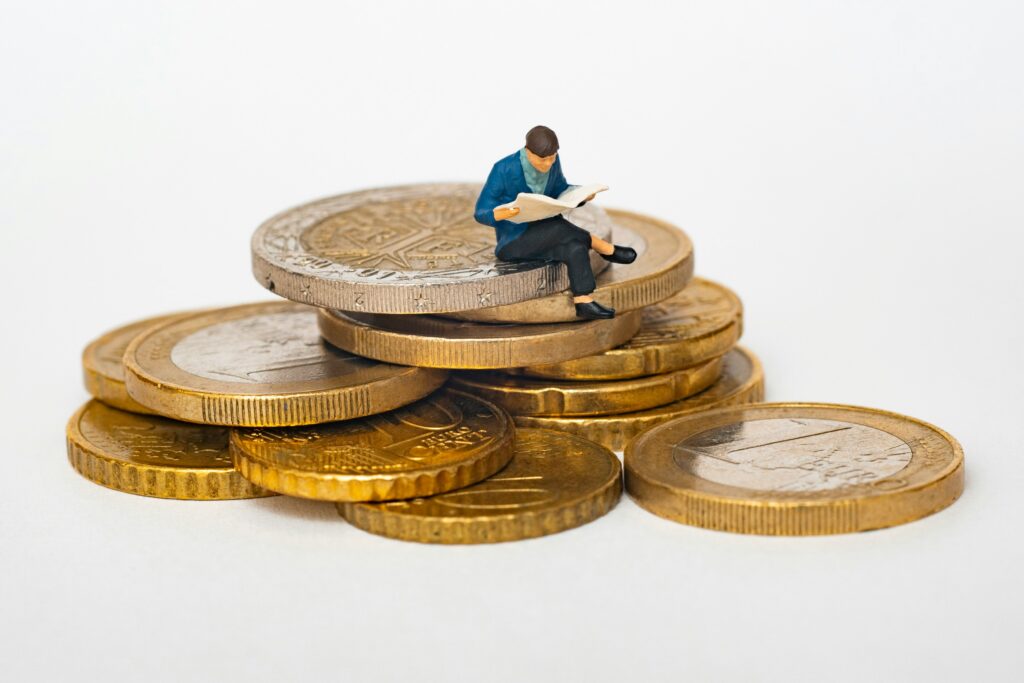
Long before a child can read a bank statement, they can understand a jar of coins. There’s something real about the weight of actual coins in your hand, a feeling that gets lost once money turns into a number on a screen. The CFPB says children ages 3 to 5 are usually too young for abstract financial ideas. It suggests simple ones instead: you earn money by working, you may have to wait and save before you buy, every purchase is a choice, and needs are different from wants. A three-jar system, spend, save and give, lets a small child sort those ideas with their hands.
The exact split doesn’t matter much at this age. What matters is the repeated act of dividing money into purposes instead of treating it as one pile to spend on whatever is closest. Plenty of grown adults with bank accounts never quite got this down, and honestly, we’d probably all do better with a three-jar system in our heads.
Turn Grocery Shopping Into an Unannounced Economics Class
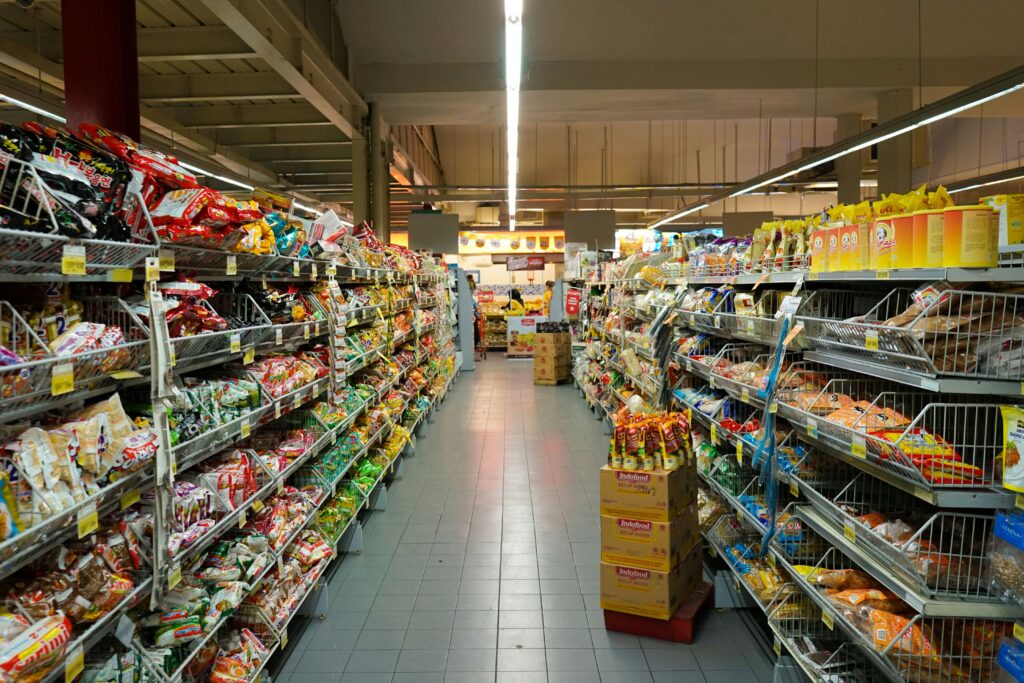
Hand a kid old enough to use a calculator or a phone a real budget, say twenty dollars for a specific list, and let them do the math as items go into the cart. They’ll notice on their own that the cereal with the cartoon on the box often costs a lot more than the plain one on the shelf below. Run out of budget before the list is finished and something goes back. No worksheet can match that. You don’t have to announce that it’s a lesson. It tends to land better when you don’t, and you don’t need to say a single preachy word about it. Budgets are limits, not suggestions, and kids pick that up fast when the stakes are small but real.
Let Them Earn, Not Just Receive
Parents disagree about whether allowance should be tied to chores or given as a set amount, and both can work at different ages. A set amount teaches budgeting without turning every chore into a wage negotiation. Optional earning teaches a separate lesson: extra chores, a lemonade stand or pet-sitting for a neighbor show that income comes from doing something useful for someone else. Money doesn’t just show up because you live in a house with people who love you. If that part never gets taught, it can turn into a sense of entitlement by the teen years, when the stakes get higher.
Make Saving Visible and, Ideally, Slightly Exciting
Compound growth is hard for anyone to feel in the abstract. That is why the SEC’s Investor.gov runs a calculator to show how much money can grow using “the power of compound interest.” A savings poster or a thermometer chart, colored in as a goal gets closer, does the same job for a child. Slow progress becomes something they can see. Compound interest is one of the more magical ideas in personal finance, and it turns saving into a game with a finish line. Most people remember saving up for something they really wanted and how good it felt to finally buy it.
Offer to match part of what your child saves toward a goal, like a bike, a game or a trip. It gives them a small preview of what an employer retirement match or an interest-bearing account will do later. They learn that saving gets rewarded with money, too, and not only with praise. That’s a lesson worth feeling early.
Use Games for Teaching Kids About Money
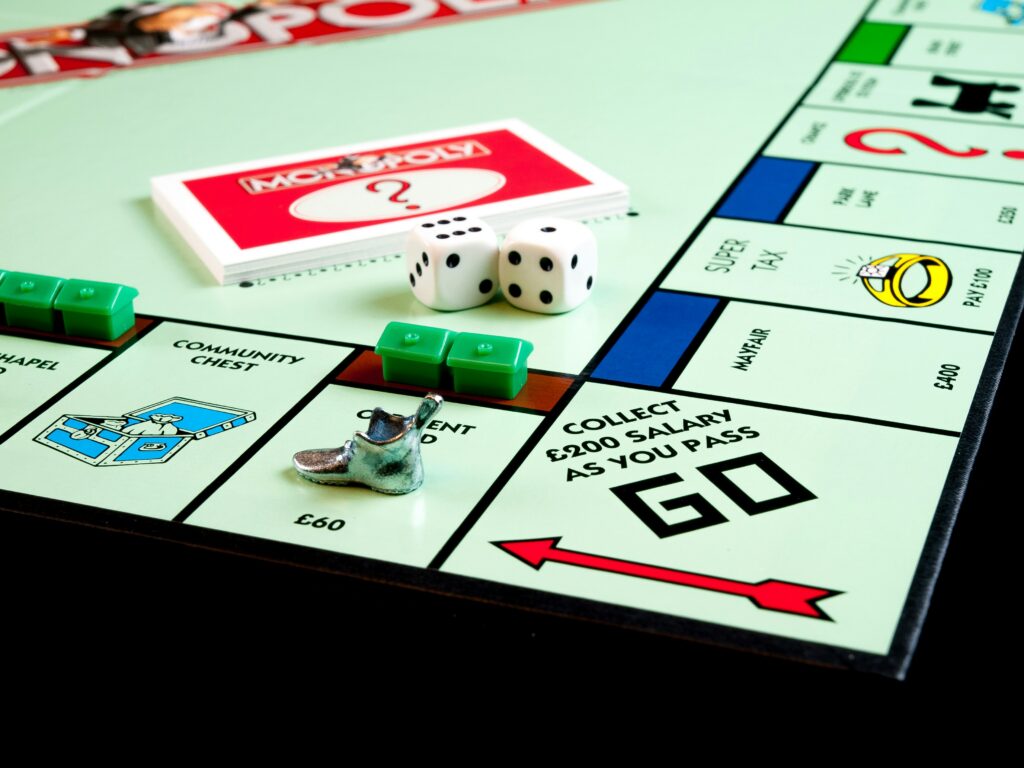
Board games have taught money concepts for close to a century. Monopoly, first published by Parker Brothers in 1935, is slow, but it is still a decent introduction to property, rent and the real sting of running out of cash. Newer budgeting and investing apps built for teens add more detail as kids get older. The format matters more than the game. In play, a mistake costs pretend money and a little pride. In a lecture, the same mistake can feel like judgment. Monopoly can run forever and sometimes ends with someone flipping the board, as anyone who has played it knows. Still, we rarely resent losing a game the way we resent being lectured.
Talk About Money Honestly, Including the Uncomfortable Parts
The most useful thing a parent can do costs nothing: talk about money out loud in front of your kids. The CFPB says money habits and norms really start to take shape between ages 6 and 12, as children watch how family and peers handle money. You don’t need to share exact numbers. Explain why an impulse buy gets a no this month. Say what a bill is for when it arrives. Admit it when a money decision didn’t work out. Kids who only see money handled in silence can easily decide that money trouble is something to hide, and that idea can follow people into adulthood and keep them from asking for help.
Teaching Kids About Money as They Grow
As kids get older, the conversation gets more concrete. The CFPB says young people from 13 to 21 solidify the financial knowledge and decision-making skills that matter more in their daily lives. Bank accounts replace jars, and by the time college costs become the real topic, a teen who has done their own grocery math for years has a head start. If your own budget needs a refresh while you teach theirs, a few banking adjustments are worth a look at the same time.
The goal is not a kid who never makes a money mistake. Plenty of adults can’t manage that. Aim for a kid who understands money well enough to make the mistakes cheap, early and easy to recover from, long before the stakes get big enough to hurt. Parents who overthink it and wait for the perfect lesson plan often teach less than the ones who simply talk about everyday money honestly, year after year. Kids pick up money the way they pick up language, by being around it, not by drilling grammar.
Teaching Kids About Money: Frequently Asked Questions
What age should kids start learning about money?
The CFPB’s Money as You Grow program starts at ages 3 to 5. Children that young are usually too young for abstract ideas, so it suggests simple ones: you earn money by working, you may have to wait and save before you buy, every purchase is a choice, and needs differ from wants.
Should allowance be tied to chores?
There is no single right answer. Many families combine a set allowance, which teaches budgeting, with optional paid chores, which teach that income comes from work. A set amount keeps every chore from turning into a wage negotiation, while the extra jobs show a child that doing something useful for someone else is how money gets earned.
What is the first step in teaching kids about money?
A three-jar system, spend, save and give, is an easy start because a child can sort real coins with their hands. It fits the CFPB’s early-childhood ideas about saving, waiting before you buy, and telling needs from wants. The exact split matters less than doing it every time money comes in.
How do I teach a teenager about money?
Give teens real tools: a bank account, a budget for their own spending, and honest talk about bills, credit and the family’s finances. The CFPB says young people from 13 to 21 solidify the financial knowledge and decision-making skills that matter more in their daily lives, so this is the age to let them make real choices.
This article is for general information only and is not financial advice. Talk to a qualified financial professional about decisions specific to your family.
 Madeline Marshall